As a broad 2026 national reference, Angi reports that many professional remediation projects fall between $1,223 and $3,757, with an average near $2,368. Those figures are not Jackson bids. A small accessible surface project, an HVAC system, a flooded finished basement, and a concealed wall loss should not be priced from the same range.
Seven factors that move the total
- Extent: visible square footage is not the same as the work area after containment and demolition.
- Access: low crawl spaces, attics, wall cavities, and HVAC components require different labor and controls.
- Material: hard surfaces may be cleanable; wet porous materials may need disposal and replacement.
- Water source: clean-water leaks, long-term humidity, groundwater, and sewage create different scopes.
- Containment: barriers, negative pressure, HEPA filtration, and decontamination add setup and monitoring.
- Repair: plumbing, roofing, drainage, drywall, insulation, flooring, and painting may be separate trades.
- Verification: an independent inspection or sampling protocol adds cost but may reduce ambiguity.
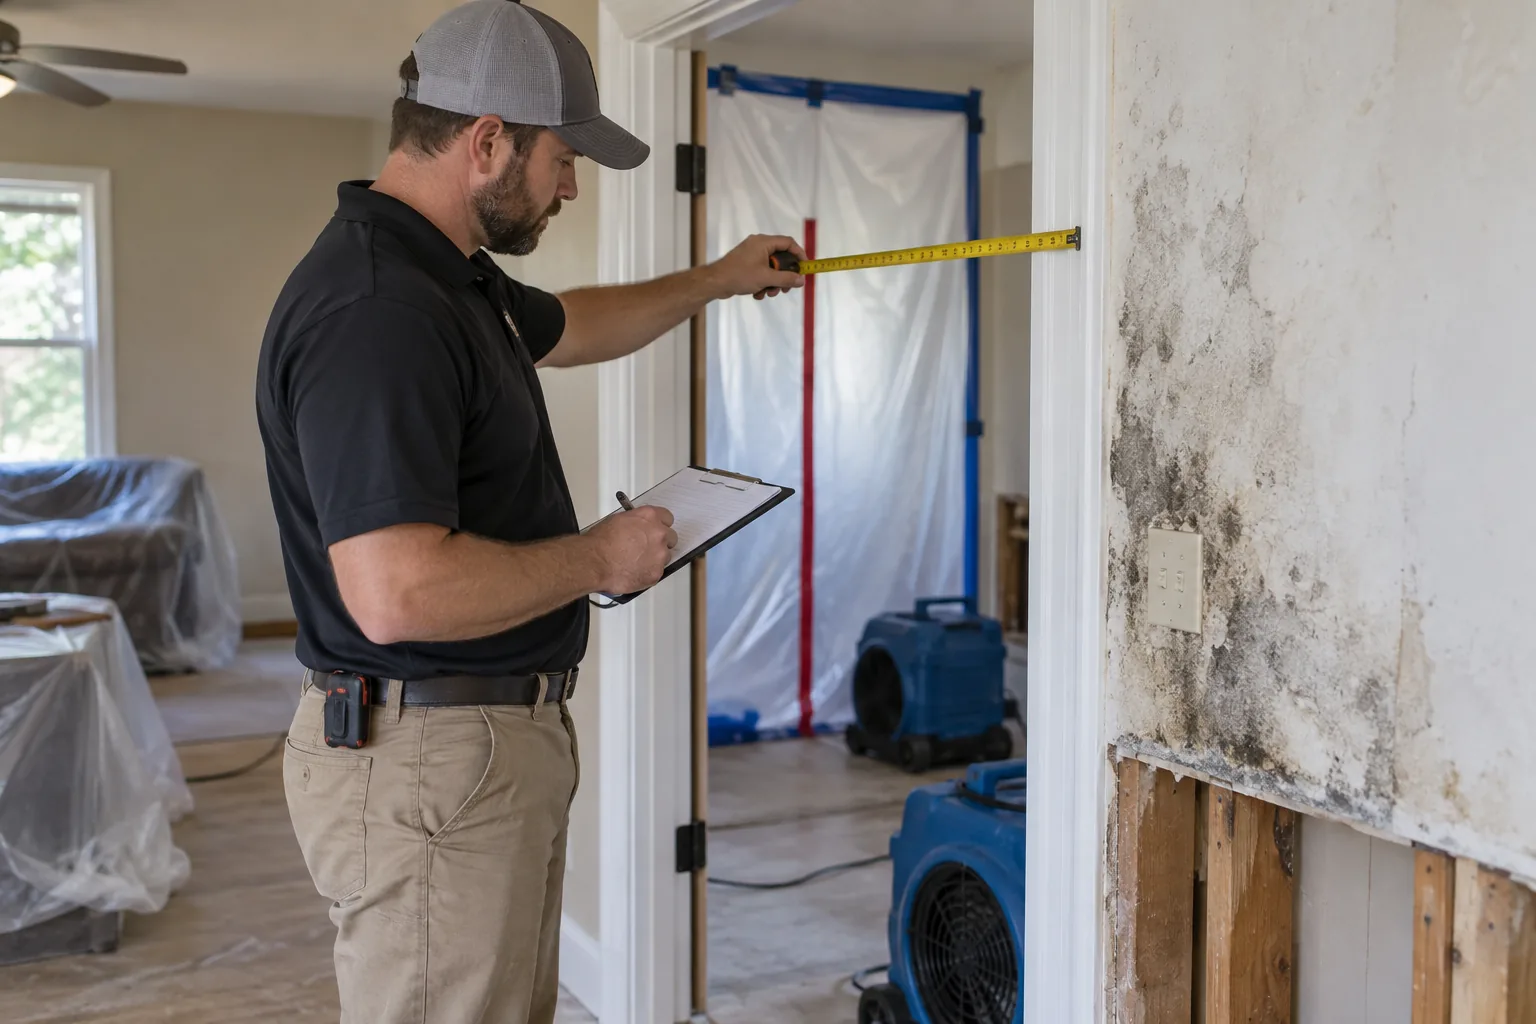
A line-item quote anatomy
| Line item | What the quote should clarify |
|---|---|
| Assessment | Accessible areas, moisture measurements, assumptions, and exclusions |
| Containment | Work-zone boundary, pressure control, HVAC isolation, and access |
| Removal | Exact materials and disposal quantity |
| Cleaning | Methods, surfaces, equipment, and contents handling |
| Drying | Equipment, power, duration assumptions, and target readings |
| Repairs | Trade work, finish level, matching, permits, and warranty |
| Verification | Who performs it, criteria, timing, and whether sampling is included |
Use a change-order trigger, not a blank check
Hidden damage is real, but the contract can still define how it will be handled. Ask the contractor to stop, document, and price additional work when demolition reveals conditions beyond the original boundary. Agree on who can approve changes and whether labor and material rates are fixed.
Insurance questions to ask early
Ask whether the cause of water is covered, whether mold has a sublimit, what documentation is required, whether emergency mitigation may begin before inspection, and how discarded material should be documented. Flood coverage is typically separate from a standard homeowners policy.
Questions homeowners ask
Does homeowners insurance cover mold removal?
Should I choose the lowest mold-removal estimate?
Is testing always an extra cost?
Sources and standards
Editorial guidance on this page is based on current public-health and contractor resources. A property-specific scope still requires an on-site assessment.